by Farley Webmaster | Oct 3, 2019
Technology is changing the way we do almost everything, and real estate transactions are no exception. In fact, a new crop of tech companies wants to revolutionize the way we buy and sell homes. iBuyer startups like Opendoor, Offerpad, and Properly are rapidly expanding into new territories, and now established players, like Zillow, are heavily involved in the action, especially in the Denver metro real estate market. Also known as Direct Buyers, these companies use computer algorithms to provide sellers with a quick cash offer to buy their home. While the actual market share of iBuyers remains small, their big advertising budgets have helped create a noticeable buzz in the industry. This has left many of our clients curious about them and how they work. In this article, we explain their business model, weigh the pros and cons of working with an iBuyer, and share strategies you can use to protect yourself if you choose to explore this new option to buy or sell your home.
FIRST, HOW DOES THE iBUYER PROCESS WORK? While each company operates a little differently, the basic premise is the same. A seller (or seller’s agent) completes a brief online form that asks questions about the size, features, and condition of the property. Some also request digital photos of the home. The iBuyer will use this information to determine whether or not the home fits within their “buy box,” or set of criteria that matches their investment model. They are generally looking for houses they can easily value and “flip.” In most cases, their ideal property is a moderately priced, single-family home located in a neighborhood with many similar houses. The property shouldn’t require any major renovations before listing.1 These qualities make it easier to assess value (lots of comparable sales data) and help to reduce risk and minimize carrying costs. Once the iBuyer has used their algorithm to determine the amount they are willing to pay, they will email an offer to the seller, usually within a few days. The offer should also disclose the company’s service fee, which is typically between 7% and 12% of the purchase price.2 If the seller accepts, an in-person visit and inspection are scheduled. The iBuyer will ask for a reduction in price to cover any defects they find during the process. Once the sale closes, they will make the necessary updates and repairs and then resell the home on the open market.
WHAT ARE THE PROS AND CONS OF SELLING TO AN iBUYER? Of course, the biggest benefit of selling your home to an iBuyer is convenience. For some homeowners, the stress and disruption of preparing and listing their home can feel overwhelming. And what busy family with kids and pets wouldn’t want to skip the hassle of keeping their house “show ready” for potential buyers? Additionally, many sellers like the predictability of a cash buyer and the flexibility to choose their closing date. However, this added convenience does come at a cost. An iBuyer is an investor looking to make a profit. So their purchase offer is usually below true market value. When you tack on service fees of up to 12% and deductions for updates and repairs, studies show that sellers who work with iBuyers net a lower amount than those that list the traditional way.3 In fact, a MarketWatch investigation found that transactions involving iBuyers net the seller 11% less than if they would have sold their home with an agent on the open market.2
WHAT ARE THE PROS AND CONS OF BUYING FROM AN iBUYER? Buying a home from an iBuyer is a lot like buying a home from any investor. The pros are that it’s usually clean, neutral, and moderately updated. You’ll often find fresh paint and modern finishes. And because it’s uninhabited (no one is living there), you don’t have to work around a seller’s schedule to see the home. However, there are some pitfalls to avoid when working with iBuyers. Speed is of the essence, so sometimes the renovations are rushed and the quality can suffer. Also, their investment margins don’t leave much room for negotiating a price reduction or additional repairs. That leaves buyers —who have already invested hundreds of dollars in an inspection—little recourse if any issues are uncovered.4 That’s one of the reasons we always recommend viewing properties with an agent. During your visit, a real estate professional can point out any “red flags” at the home, provide background information about the neighborhood, and help you assess its true market value. That way, you don’t invest time and money in a high-risk or overpriced property. Safety is also a concern. Some companies allow buyers to access their homes via a smartphone app. While it may seem convenient, it provides an easy way for squatters and others to enter the home illegally.5 Luckily, since most iBuyers (and traditional sellers) pay a buyer agent’s commission, you can benefit from the guidance and expertise of a real estate professional … at no cost to you!
HOW CAN I PROTECT MYSELF IF I CHOOSE TO WORK WITH AN iBUYER? While it may seem like the “quick and easy” way to go, working with an iBuyer can present some unique challenges. For example, they are notorious for presenting a strong initial purchase offer and then whittling it down with a long list of costly updates and repairs once they complete their inspection.2 And unlike a traditional buyer who is incentivized to make a deal work, iBuyers can easily walk away if you don’t meet their demands. Just like you wouldn’t go to court without a lawyer, you shouldn’t enter into a real estate transaction without an advocate to represent you. Having a professional agent on your side can be especially important when negotiating with an iBuyer. Remember, they employ sophisticated representatives and a team of lawyers who are focused on maximizing their profits, not yours. You need someone in your corner who has the skills and knowledge to ensure you get a fair deal and who understands the terms of their contracts, so you don’t encounter any unpleasant surprises along the way. Overall, we think the emergence of new technology that helps to streamline the real estate process is exciting. And if we believe a client can benefit from working with an iBuyer, we present it as an option. But there is—inevitably—a cost to the convenience. After all, most iBuyers eventually list the properties they acquire on the open market, which is still the best place to find a buyer if you want to maximize the sales price of your home.
| EXPLORE YOUR OPTIONS Do you want to learn more about iBuyers and other options currently available in the Boulder area to buy or sell your home? We can help you determine the best path, given your unique circumstances. Contact us at 303-475-6269 to schedule a free, no-obligation consultation! |
Sources:
- The Dallas Morning News – https://www.dallasnews.com/business/real-estate/2019/07/11/so-called-ibuyer-real-estate-firms-pitch-programs-to-buy-your-house-help-you-hunt-for-another/
- MarketWatch – https://www.marketwatch.com/story/selling-your-home-to-an-ibuyer-could-cost-you-thousands-heres-why-2019-06-11
- Forbes – https://www.forbes.com/sites/alyyale/2019/08/16/study-shows-ibuyers-cost-home-sellers-thousands-is-convenience-worth-the-price/#697ac0c42269
- US News & World Report – https://realestate.usnews.com/real-estate/articles/what-to-expect-when-buying-a-home-from-an-ibuyer
- Inman – https://www.inman.com/2019/09/11/police-arrest-couple-found-squatting-in-opendoor-home-with-their-kids/
by Farley Webmaster | Jun 13, 2018
Whatever your reasons are for relocating to a new area, the process can feel overwhelming.
Whether you’re moving across across town or across the country, you’ll be changing more than your address. Besides a new house, you may also be searching for new jobs, schools, doctors, restaurants, stores, service providers and more.
Of course you’ll need to pack, make moving arrangements, and possibly sell your old home. With so much to do, you may be wondering: Where do I start?
In this guide, we outline seven steps to help you get prepared, get organized, and get settled in your new community. Our hope is to alleviate the hassle of relocating—so you can focus on the exciting adventure ahead!
1. Gather Information
If you’re unfamiliar with your new area, start by doing some research.1 Look for data on average housing prices, demographics, school rankings and crime statistics. Search for maps that illustrate local geography, landmarks, public transportation routes and major interstates. If you’re moving across the country, research climate and seasonal weather patterns.
Check out local newspapers and blogs for information on political issues and developments that could impact your new community. You may also want to search for online forums and Facebook Groups relevant to your new area. These can be a great place to find information, ask questions and just observe local attitudes and outlooks.
If you’re relocating for a job, find out if your new employer offers any relocation assistance. Many large corporations have a designated human resources professional to assist employees with relocation efforts, while others may contract this service out to a third party. Some employers will also cover all or a portion of your relocation and moving costs.
By gathering this information up front, you’ll be better prepared to make informed decisions down the road.
| Let us know if you’d like assistance with your information gathering process. We have a wealth of knowledge about this area, and we keep a number of reports and statistics on file. We would be happy to share information and answer any questions you may have. |
2. Identify Your Ideal Neighborhoods
Once you’ve sufficiently researched your new area, you can start to identify your ideal neighborhoods.
The first step is to prioritize your “needs” and “wants.” Consider factors such as budget; commute time; quality of schools; crime rate; walkability; access to public transportation; proximity to restaurants, shopping, and place of worship; and neighborhood vibe.
If possible, visit the area in person to get a feel for the community. If you’re comfortable, strike up conversations with local residents and ask about their experiences living in the area.
Still not sure which neighborhood is the best fit for you and your family? Contact a local real estate agent for expert assistance. It’s usually the most efficient and effective way to narrow down your options.
| We provide neighborhood assessments and advice as a free service if you’re relocating to Boulder, Colorado or near by areas. Or, if you’re moving out of town, we can refer you to a local agent who can help. |
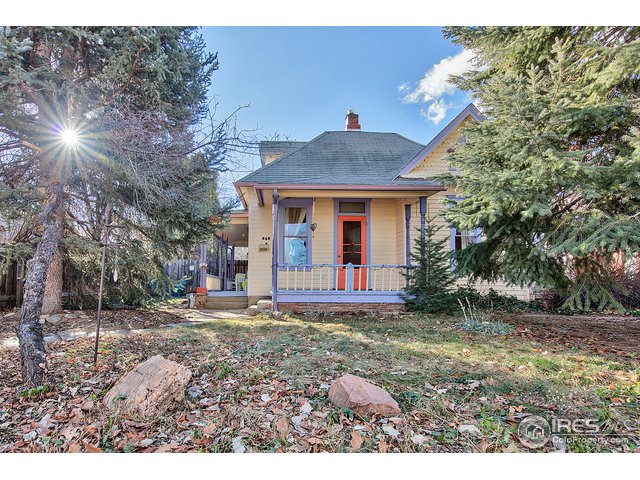
Charming Bungalow 1/2 Mile to Pearl Street 646 Marine Street, Boulder, 80302
3. Find Your New Home (and Sell Your Old One)
Once you’ve narrowed down your list of preferred neighborhoods, it’s time to start looking for a home. If you haven’t already contacted a real estate agent, now is the time. They can search for current property listings that meet your needs, typically at no cost to you.
Create another list of “needs” and “wants,” but this time for your new home. Include your basic requirements for square footage, bedrooms and bathrooms, but also think about what other factors are important to you and your family. An updated kitchen? A large backyard? Double sinks in the master bathroom?
Narrow your list down to your top 10 and prioritize them in order of importance.2 This will give you a good starting point to begin your home search. Unless you have an unlimited budget, don’t expect to find a home with everything on your list. But having a prioritized list can help you (and your agent) understand which home features are the most important, and which ones you may be willing to sacrifice.
If you already own a home, you’ll also need to start the process of selling it or renting it out. A real estate agent can help you evaluate your options based on current market conditions. He or she can also give you an idea of how much equity you have in your current home so you know how much you can afford to spend on your new one.
Your agent can also advise you on how to time your sale and purchase. While some buyers are able to qualify for and cover the costs of two concurrent mortgages, many are not. There are a number of options available, and a skilled agent can help you determine the best course given your circumstances.
| We would love to assist you if you have plans to buy or sell a home in Boulder, Colorado. Please contact us to schedule a free consultation so we can discuss your unique needs and devise a custom plan to make your relocation as seamless as possible. If you’re relocating outside of Colorado, we can help you find a trusted agent in your new city. |
4. Prepare for Your Departure
While everyone considers packing a fundamental part of moving, we often overlook the emotional preparation that needs to take place. If you have children, this can be especially important. Communicate the move in an age-appropriate way, and if possible take them on a tour of your new home and neighborhood. This can alleviate some of the mystery and apprehension around the move.4
Allow yourself plenty of time to pack up your belongings. Before you start, gather supplies, including boxes, tape, tissue paper and bubble wrap. Begin with non-essentials—such as off-season clothes or holiday decorations—and sort items into four categories: take, trash, sell and donate/give away.5
To make the unpacking process easier, be sure to label the top and sides of boxes with helpful information, including contents, room, and any special instructions. Keep a master inventory list so you can refer back to it if something goes missing.
If you will be using a moving company, start researching and pricing your options. To ensure an accurate estimate of your final cost, it’s best to have them conduct an in-person walkthrough. Make sure you’re working with a reputable company, and avoid paying a large deposit before your belongings are delivered.6
If you plan to drive to your new home, map out the route. And, if necessary, make arrangements for overnight accommodations along the way. If driving is not a good option, you may need to have your vehicles transported and make travel arrangements for you, your family and your pets.
Lastly, if you will be leaving friends or family behind, schedule final get-togethers before your departure. The last days before moving can be incredibly hectic, so make sure you block off some time in advance for proper goodbyes.
| Looking for a reputable moving company? We are happy to provide referrals, as well as recommendations on where to procure packing supplies in our area. |
Learn more about the neighborhoods that make up Boulder, Colorado
5. Prepare for Your Arrival
To make your transition go smoothly, prepare for your arrival well before moving day. Depending on how long your belongings will take to arrive, you may need to arrange for temporary hotel accommodations. If you plan to move in directly, pack an “essentials box” with everything you’ll need for the first couple of nights in your new home, such as toiletries, toilet paper, towels, linens, pajamas, cell phone chargers, snacks, pet food and a change of clothes.7 This will keep you from searching through boxes after an exhausting day of moving.
Arrange in advance for your utilities to be turned on, especially essentials like water, electricity and gas. (And while you’re at it, schedule a shut-off date for your current utilities.) Update your address on all accounts and subscriptions and arrange to have your mail forwarded through the postal service. If you have children, register them for their new school or daycare and arrange for the transfer of any necessary records.
You may want to have the house professionally cleaned before moving in. And if you plan to remodel, paint or install new flooring, it’s easier to have it done before you bring in all of your belongings.8 However, it’s not always feasible without someone you trust locally who can supervise. Another option is to keep a portion of your things in storage while you complete some of these projects.
If there are no window treatments, you may need to install some (or at least put up temporary privacy film), especially in bedrooms and bathrooms. And if appliances are missing, consider purchasing them ahead of time and arranging for delivery and installation shortly after you arrive. Just be sure to check measurements and installation instructions carefully so you aren’t stuck with an appliance that doesn’t fit or that requires costly modifications to your new home.
If you own a car, check the requirements for a driver’s license and vehicle registration in your new area and contact your insurance company to update your policy.8 If you will rely on public transportation, research options and schedules.
| If you’re relocating to Boulder, we can help! We offer “VIP Relocation Assistance” to all of our buyer clients. Contact us for a list of preferred hotels, utility providers, housekeepers, contractors and more! |
6. Get Settled In Your New Home
While staring at an endless pile of boxes can feel daunting, you should take advantage of this opportunity to make a fresh start. By creating a plan ahead of time, you can ensure your new house is thoughtfully laid out and well organized.
If you followed our suggestion to pack an “essentials box” (see Step 5), you should have easy access to everything you’ll need to get you through the first couple of nights in your new home. This will allow you some breathing room to unpack your remaining items in a deliberate manner, instead of rushing through the process.7
If you have young children, consider unpacking their rooms first. Seeing their familiar items can help them establish a sense of comfort and normalcy during a confusing time. Then move on to any items you use on a daily basis.10
Pets can also get overwhelmed by a new, unfamiliar space. Let them adjust to a single room first, which should include their favorite toys, treats, food and water bowl, and a litter box for cats. Once they seem comfortable, you can gradually introduce them to other rooms in the home.11
As you unpack, make a list of items that need to be purchased so you’re not making multiple trips to the store. Also, start a list of needed repairs and installations. If you have a home warranty, find out what’s covered and the process for filing a service order.
Although you may be eager to get everything unpacked, it’s important to take occasional breaks. Have some fun, relax and explore your new hometown!
| Need help with unpacking, organizing or decorating your new home? Contact us for a list of recommended professionals in Boulder. And when you’re ready to start exploring local “hot spots,” we’d love to fill you in on our favorite restaurants, stores, parks and other attractions! |
Get an insider’s guide to Boulder
7. Get Involved In Your New Community
Studies show that moving can lead to feelings of loneliness and depression. People who have recently moved tend to be isolated socially, more stressed, and less likely to participate in exercise and hobbies. However, there are ways to combat these negative effects.12
First, get out and explore. In a 2016 study, recent movers were shown to spend less time on physical activities and more time on their computers, which has been proven to lead to feelings of depression and loneliness. Instead, get out of your house and investigate your new area. And if you travel by foot, you’ll gain the advantages of fresh air and exercise.12
Combat feelings of isolation by making an effort to meet people in your new community. Find a local interest group, take a class, join a place of worship or volunteer for a cause. Don’t wait for friends to come knocking on your door. Instead, go out and find them.
Finally, be a good neighbor. Make an effort to introduce yourself to your new neighbors, invite them over for coffee or dinner, and offer assistance when they need it. Once you’ve developed friendships and a support system within your new neighborhood, it will truly start to feel like home.
| Want more ideas on how to get involved in your community? Contact us for a free copy of our report, “Welcome Home: 10 Tips to Turn Your Neighborhood Into a Hometown Haven.” |
LET’S GET MOVING
While moving is never easy, these seven steps offer an action plan to get you started on your new adventure. To avoid getting overwhelmed, focus on one step at a time. And don’t hesitate to ask for help!
In a 2015 study, 61 percent of participants ranked moving at the top of their stress list, above divorce and starting a new job.13 But with a little preparation—and the right team of professionals to assist you—it is possible to have a positive relocation experience.
We specialize in assisting home buyers and sellers with a seamless and “less-stress” relocation. Along with our referral network of movers, handymen, housekeepers, decorators, contractors and other service providers, we can help take the hassle and headache out of your upcoming move. Give us a call or message us to schedule a free, no-obligation consultation!
_______________________________________________________________________________
Sources:
- You Move Me –
https://www.youmoveme.com/us/blog/105-tips-for-a-successful-relocation
- com –
https://www.houselogic.com/buy/house-hunting/must-have-items/
- Livestrong –
https://www.livestrong.com/article/436651-the-effects-of-sunlight-fresh-air-on-the-body/
- Parents Magazine –
https://www.parents.com/parenting/money/buy-a-house/make-moving-easier-on-you-and-your-kids/
- The Spruce –
https://www.thespruce.com/starting-to-pack-for-your-move-2436470
- com –
https://www.moving.com/tips/hiring-quality-movers/
- The Spruce –
https://www.thespruce.com/unpack-your-entire-home-2435815
- com –
https://www.houselogic.com/buy/moving-in/before-you-move/
- HGTV –
https://www.hgtv.com/design/real-estate/moving-checklist
- com –
https://www.moving.com/tips/how-to-unpack-and-organize-your-house/
- ASPCA –
https://www.aspca.org/pet-care/general-pet-care/moving-your-pet
- Psychology Today –
https://www.psychologytoday.com/us/blog/is-where-you-belong/201607/why-youre-miserable-after-move
- The Daily Express –
https://www.express.co.uk/news/uk/574171/Divorce-stressful-moving-home
SaveSave
SaveSave
by Farley Webmaster | Mar 13, 2018
Don’t wait until you’re ready to move to start preparing financially to buy a home.
If you’re like the vast majority of home buyers, you will choose to finance your purchase with a mortgage loan. By preparing in advance, you can avoid the common delays and roadblocks many buyers face when applying for a mortgage.
The requirements to secure a mortgage may seem overwhelming, especially if you’re a first-time buyer. But we’ve outlined three simple steps to get you started on your path to homeownership.
Even if you’re a current homeowner, it’s a good idea to prepare in advance so you don’t encounter any surprises along the way. Lending requirements have become more rigorous in recent years, and changes to your credit history, debt levels, job type and other factors could impact your chances of approval.
It’s never too early to start preparing to buy a home. Follow these three steps to begin laying the foundation for your future home purchase today!
STEP 1: CHECK YOUR CREDIT SCORE
Your credit score is one of the first things a lender will check to see if you qualify for a loan. It’s a good idea to review your credit report and score yourself before you’re ready to apply for a mortgage. If you have a low score, you will need time to raise it. And sometimes fraudulent activity or erroneous information will appear on your report, which can take months to correct.
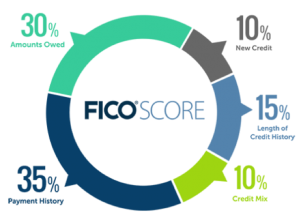
The credit score most lenders use is your FICO score, a weighted score developed by the Fair Isaac Corporation that takes into account your payment history (35%), amounts owed (30%), length of credit history (15%), new credit (10%), and credit mix (10%).1
Base FICO scores range from 300 to 850. A higher FICO score will help you qualify for a lower mortgage interest rate, which will save you money.2
By federal law, you are entitled to one free copy of your credit report every 12 months from each of the three major credit bureaus (Equifax, Experian and Transunion). Request your free credit report at https://www.annualcreditreport.com.
Minimum Score Requirements
To qualify for the lowest interest rates available, you will usually need a FICO score of 760 or higher. Most lenders require a score of at least 620 to qualify for a conventional mortgage.3
If your FICO score is less than 620, you may be able to qualify for a non-conventional mortgage. However, you should expect to pay higher interest rates and fees. For example, you may be able to secure an FHA loan (one issued by a private lender but insured by the Federal Housing Administration) with a credit score as low as 580 if you can make a 3.5 percent down payment. And FHA loans are available to applicants with credit scores as low as 500 with a 10 percent down payment.4
Increase Your Credit Score
There’s no quick fix for a low credit score, but the following steps will help you increase it over time.5
1. Make Payments on Time
At 35 percent, your payment history accounts for the largest portion of your credit score. Therefore, it’s crucial to get caught up on any late payments and make all of your future payments on time.
If you have trouble remembering to pay your bills on time, set up payment reminders through your online banking platform, a free money management tool like Mint, or an app like BillMinder.
2. Avoid Applying for New Credit You Don’t Need
New accounts will lower your average account age, which could negatively impact your length of credit history. Also, each time you apply for credit, it can result in a small decrease in your credit score.
The exception to this rule? If you don’t have any credit cards—or any credit accounts at all—you should open an account to establish a credit history. Just be sure to use it responsibly and pay it off in full each month.
If you need to shop for a new credit account, for example, a car loan, be sure to complete your loan applications within a short period of time. FICO attempts to distinguish between a search for a single loan and applications to open several new lines of credit by the window of time during which inquiries occur.
3. Pay Down Credit Cards
When you pay off your credit cards and other revolving credit, you lower your amounts owed, or credit utilization ratio (ratio of account balances to credit limits). Some experts recommend starting with your highest-interest debt and paying it off first. Others suggest paying off your lowest balance first and then rolling that payment into your next-lowest balance to create momentum.
Whichever method you choose, the first step is to make a list of all of your credit card balances and then start tackling them one by one. Make the minimum payments on all of your cards except one. Pay as much as possible on that card until it’s paid in full, then cross it off your list and move on to the next card.
Debt Interest Rate Total Payoff Minimum Payment
| Debt |
Interest Rate |
Total Payoff |
Minimum Payment |
| Credit Card 1 |
12.5% |
$460 |
$18.40 |
| Credit Card 2 |
18.9% |
$1,012 |
$40.48 |
| Credit Card 3 |
3.11% |
$6,300 |
$252 |
4. Avoid Closing Old Accounts
Closing an old account will not remove it from your credit report. In fact, it can hurt your score, as it can raise your credit utilization ratio—since you’ll have less available credit—and decrease your average length of credit history.
Similarly, paying off a collection account will not remove it from your report. It remains on your credit report for seven years, however, the negative impact on your score will decrease over time.
5. Correct Errors on Your Report
Mistakes or fraudulent activity can negatively impact your credit score. That’s why it’s a good idea to check your credit report at least once per year. The Federal Trade Commission has instructions on their website for disputing errors on your report.
While it may seem like a lot of effort to raise your credit score, your hard work will pay off in the long run. Not only will it help you qualify for a mortgage, a high credit score can help you secure a lower interest rate on car loans and credit cards, as well. You may even qualify for lower rates on insurance premiums.6
STEP 2: SAVE UP FOR A DOWN PAYMENT AND CLOSING COSTS
The next step in preparing for your home purchase is to save up for a down payment and closing costs.
Down Payment
When you purchase a home, you typically pay for a portion of it in cash (down payment) and take out a loan to cover the remaining balance (mortgage).
Many first-time buyers wonder: How much do I need to save for a down payment? The answer is … it depends.
Generally speaking, the higher your down payment, the more money you will save on interest and fees. For example, you will qualify for a lower interest rate and avoid paying for mortgage insurance if your down payment is at least 20 percent of the property’s purchase price. But what if you can’t afford to put down 20 percent?
On a conventional loan, you will be required to purchase private mortgage insurance (PMI) if your down payment is less than 20 percent. PMI is insurance that compensates your lender if you default on your loan.7
PMI will cost you between 0.3 to 1.5 percent of the overall mortgage amount each year.8 So, on a $100,000 loan, you can expect to pay between $300 and $1500 per year for PMI until your mortgage balance falls below 80 percent of the appraised value.9 For a conventional mortgage with PMI, most lenders will accept a minimum down payment of five percent of the purchase price.7
If a five-percent down payment is still too high, an FHA-insured loan may be an option for you. Because they are guaranteed by the Federal Housing Administration, FHA loans only require a 3.5 percent down payment if your credit score is 580 or higher.7
The downside of getting an FHA loan? You’ll be required to pay an upfront mortgage insurance premium (MIP) of 1.75 percent of the total loan amount, as well as an annual MIP of between 0.80 and 1.05 percent of your loan balance on a 30-year note. There are also certain limitations on the types of loans and properties that qualify.10
There are a variety of other government-sponsored programs created to assist home buyers, as well. For example, veterans and current members of the Armed Forces may qualify for a VA-backed loan requiring a $0 down payment.7 Consult a mortgage lender about what options are available to you.
| TYPE |
MINIMUM DOWN |
ADDITIONAL FEES |
| Conventional Loan |
20% |
Qualify for the best rates and no mortgage insurance required |
| Conventional Loan |
5% |
Must purchase private mortgage insurance costing 0.3 – 1.5% of mortgage annually |
| FHA Loan |
3.5% |
Upfront mortgage insurance premium of 1.75% of loan amount and annual fee of 0.8 – 1.05% |
Current Homeowners
If you’re a current homeowner, you may have equity in your home that you can use toward your down payment on a new home. We can help you estimate your expected return after you sell your current home and pay back your existing mortgage. Contact us for a free evaluation!
Closing Costs
Closing costs should also be factored into your savings plan. These may include loan origination fees, discount points, appraisal fees, title searches, title insurance, surveys and other fees associated with the purchase of your home. Closing costs vary but typically range between two to five percent of the purchase price.11
If you don’t have the funds to pay these outright at closing, you can often add them to your mortgage balance and pay them over time. However, this means you’ll have a higher monthly payment and pay more over the long term because you’ll pay interest on the fees.
STEP 3: ESTIMATE YOUR HOME PURCHASING POWER
Once you have the required credit score, savings for a down payment and a list of all your outstanding debt obligations via your credit report, you can assess whether you are ready and able to purchase a home.
It’s important to have a sense of how much you can reasonably afford—and how much you’ll be able to borrow—to see if homeownership is within reach.
Your debt-to-income (DTI) ratio is one of the main factors mortgage companies use to determine how much they are willing to lend you, and it can help you gauge whether or not your home purchasing goals are realistic given your current financial situation.
Your DTI ratio is essentially a comparison of your housing expenses and other debt versus your income. There are two different DTI ratios that lenders consider:
Front-End Ratio
Also called the housing ratio, this is the percentage of your income that would go toward housing expenses each month, including your mortgage payment, private mortgage insurance, property taxes, homeowner’s insurance and association dues.12
To calculate your front-end DTI ratio, a lender will add up your expected housing expenses and divide it by your gross monthly income (income before taxes). The maximum front-end DTI ratio for most mortgages is 28 percent. For an FHA-backed loan, this ratio must not exceed 31 percent.13
Back-End Ratio
The back-end ratio takes into account all of your monthly debt obligations: your expected housing expenses PLUS credit card bills, car payments, child support or alimony, student loans and any other debt that shows up on your credit report.12
To calculate your back-end ratio, a lender will tabulate your expected housing expenses and other monthly debt payments and divide it by your gross monthly income (income before taxes). The maximum back-end DTI ratio for most mortgages is 36 percent. For an FHA-backed loan, this ratio must not exceed 41 percent.13
Home Affordability Calculator
To get a sense of how much home you can afford, visit the National Association of Realtors’ free Home Affordability Calculator at https://www.realtor.com/mortgage/tools/affordability-calculator.
This handy tool will help you determine your home purchasing power depending on your location, annual income, monthly debt and down payment. It also offers a monthly mortgage breakdown that projects what you would pay each month in principal and interest, property taxes, and home insurance.
The Home Affordability Calculator defaults to a back-end DTI ratio of 36 percent. If the monthly cost estimate at that ratio is significantly higher than what you’re currently paying for housing, you need to consider whether or not you can make up the difference each month in your budget.
If not, you may want to lower your target purchase price to a more conservative DTI ratio. The tool enables you to scroll through higher and lower price points to see the impact on your monthly payments so you can identify your ideal price point.
(Note: This tool only provides an estimate of your purchasing power. You will need to secure pre-approval from a mortgage lender to know your true mortgage approval amount and monthly payment projections.)
Can I Afford to Buy My Dream Home?
Once you have a sense of your purchasing power, it’s time to find out which neighborhoods and types of homes you can afford. The best way to determine this is to contact a licensed real estate agent. We help homeowners like you every day and can send you a comprehensive list of homes within your budget that meet your specific needs.
If there are homes within your price range and target neighborhoods that meet your criteria—congratulations! It’s time to begin your home search.
If not, you may need to continue saving up for a larger down payment … or adjust your search parameters to find homes that do fit within your budget. We can help you determine the right course for you.
START LAYING YOUR FOUNDATION TODAY
It’s never too early to start preparing financially for a home purchase. These three steps will set you on the path toward homeownership … and a secure financial future!
And if you are ready to buy now but don’t have a perfect credit score or a big down payment, don’t get discouraged. There are resources and options available that might make it possible for you to buy a home sooner than you think. We can help.
Want to find out if you’re ready to buy a house? Give us a call! We’ll help you review your options, connect you with one of our trusted mortgage lenders, and help you determine the ideal time to begin your new home search.
The above references an opinion and is for informational purposes only. It is not intended to be financial advice. Consult a financial professional for advice regarding your individual needs.
Sources:
1. Quicken Loans Blog –
https://www.quickenloans.com/blog/how-does-your-credit-score-affect-your-mortgage-eligibility
2. myFICO –
https://www.myfico.com/credit-education/credit-report-credit-score-articles/
3. Bankrate –
https://www.bankrate.com/mortgages/what-is-a-good-credit-score-to-buy-a-house/
4. Bankrate –
https://www.bankrate.com/finance/mortgages/7-crucial-facts-about-fha-loans-1.aspx
5. myFICO –
https://www.myfico.com/credit-education/improve-your-credit-score/
6. The Balance –
https://www.thebalance.com/having-good-credit-score-960528
7. Bankrate –
https://www.bankrate.com/mortgages/how-much-is-a-down-payment-on-a-house/
8. Bankrate –
https://www.bankrate.com/finance/mortgages/the-basics-of-private-mortgage-insurance-pmi.aspx
9. Bankrate –
https://www.bankrate.com/finance/mortgages/removing-private-mortgage-insurance.aspx
10. The Balance –
https://www.thebalance.com/fha-home-loan-pitfalls-315673
11. Investopedia –
https://www.investopedia.com/terms/c/closingcosts.asp
12. Bankrate –
https://www.bankrate.com/finance/mortgages/why-debt-to-income-matters-in-mortgages-1.aspx
13. The Lenders Network –
https://thelendersnetwork.com/fha-debt-to-income-ratio/
SaveSaveSaveSave
SaveSave
SaveSave
by Farley Webmaster | Jul 19, 2017
Understanding a home’s true market value is about more than pictures, software assessments and price-per-square-foot. Whether you’re a current homeowner thinking of selling or are house-hunting, it’s crucial you understand what factors affect home valuation. By partnering with a local market expert, sellers will avoid pricing their house out of the market (the kiss of death in real estate) and buyers will ensure they get a good deal on their next home.
So, how do you accurately calculate a home’s value? After all, the value a home is assigned by its town or county and the one it’s given when it’s listed are often dramatically different from one another. Which one is accurate and what does it all mean? Read on to learn more.
Assessed Value vs Market Value: What’s the difference?
When it comes to home value, you’ll often hear two terms, assessed value and market value.
A home’s assessed value is often the lower number of the two, and is the value given by your municipality or county. Investopedia defines assessed value as “the dollar value assigned to a property to measure applicable taxes.”1 Although property tax laws vary, assessors commonly arrive at this number by taking into account the following:
- What comparable/similar homes are selling for in your area.
- The value of recent improvements.
- Income from renting out a room or space on the property.
- How much it would cost to rebuild on the property.
A home’s market value, or Fair Market Value, is the price a buyer is willing to pay or a seller is willing to accept for a property. A skilled real estate professional will arrive at the value using a variety of metrics, including:
- External characteristics, such as lot size, home style, the condition of the home and curb appeal.
- Internal characteristics, such as the number of rooms and their size, the type and condition of the heating or HVAC system, the quality and condition of construction, the flow of the home, etc.
- The sales price of comparable homes that have sold in your area.
- Supply and demand; that is, how many buyers and sellers are in the area.
- Location; that is, the quality and desirability of your neighborhood and other community amenities.
Why are these values often so different? An assessor usually estimates your property’s market value during a reassessment or if you make a physical change or improvement to it.2 As a result, a property may not be reassessed for many years. While your home’s market value may fluctuate with the market, your home’s assessed value is more likely to remain steady.3
What Determines a Home’s Value?
You’ve likely heard the motto of real estate: “Location, location, location.” This means a home’s value relies on its location. While the home and structures on the property will likely depreciate over time, the land beneath it tends to appreciate. Why? Land is in limited supply and a growing population puts increased demand on the housing supply. As a result, values increase.4
Other factors that affect your home’s value include the function and appearance of the property, how well the home and other structures are maintained and whether the home is a lifestyle property, such as a ranch style with mountain views or beach bungalow.
Ultimately, the best indication of a home’s value is the overall supply and demand of the market. This is why we recommend you partner with a real estate professional who takes all of these factors—the assessed value, local market conditions, home features and has physically walked through and experienced your home— into consideration to determine the most accurate market value.
How to determine if a property is comparable to yours.
Both assessed value and market value are partially determined by the sales price of similar, or comparable, homes in the area. To determine if a home is comparable to yours, look for the following characteristics:
- Lot size
- Square footage
- Home style or similar architecture
- Age
- Location
While you may not find a home with the same exact characteristics as yours, you’ll likely find a few that are close. To account for any disparity, adjust the sales prices of the comparable properties. Look at the differences between your property and the one in question and determine if the differences increased or decreased the sales price and by how much. For example, if your home has two bathrooms and a similar home only has three, estimate how much that extra bathroom increased the sale price of the similar home. The adjusted sale price is the estimation of what the property would sell for if the properties were exactly the same.2
Where can you find comparable sales?
Fortunately, you can find comparable home sales in a variety of places.2
- Your local assessor’s office is able to provide a list of recent sales you can browse and compare or a sales history of a particular house, home style or neighborhood.
- Your municipality. Many cities keep local sales information in their offices or post it online.
- Online databases, such as a real estate database
- Your local newspapers may offer some real estate information in the form of quarterly sales reports in the business or real estate sections of the newspaper.
- Our office. We regularly do Comparable Market Analysis of homes in our local area.
How to calculate your home’s value.
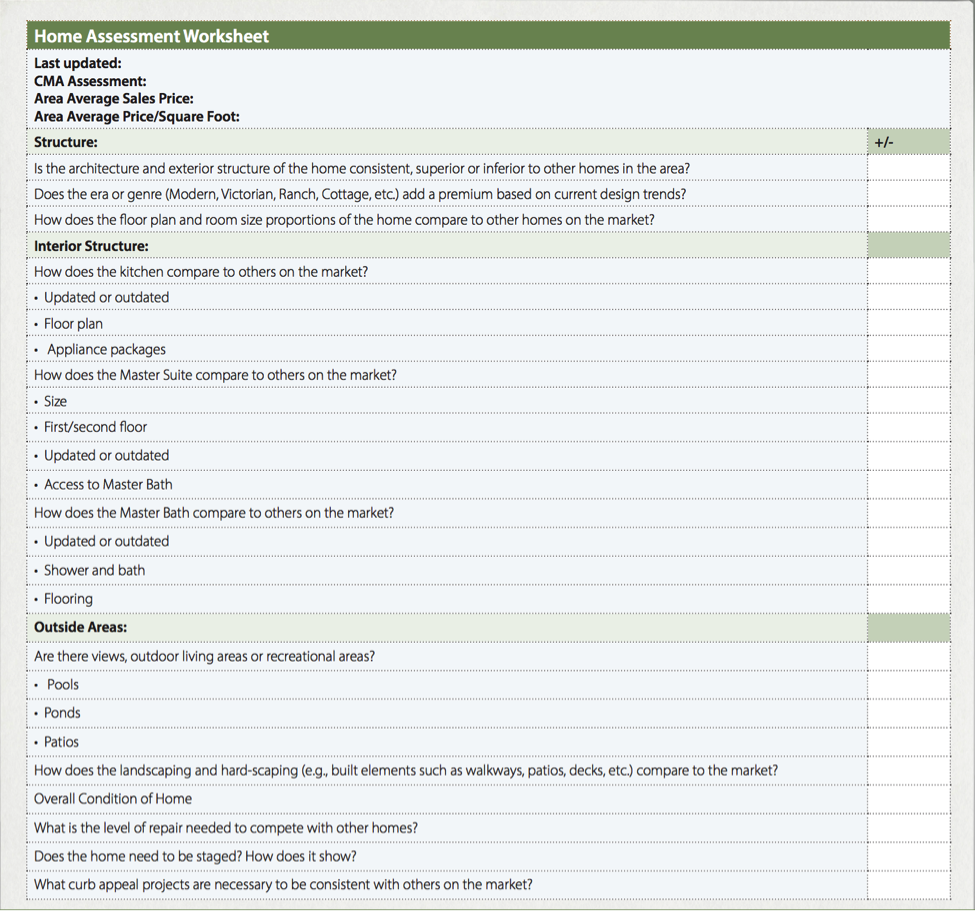
By answering a few questions about your home, property and the local market, you can begin to estimate your property’s value. We’ve also included a worksheet for you below…
Home Value Questions:
When was your home last assessed?
What was its CMA assessment value?
What is your area’s average sales price?
What is your area’s average price/square foot?
Structure:
- Is the architecture and exterior structure of the home consistent, superior or inferior to other homes in the area?
- Does the era or genre (Modern, Victorian, Ranch, Cottage, etc.) add a premium based on current design trends?
- How does the floor plan and room size proportions of the home compare to other homes on the market?
Interior Structure:
- How does the kitchen compare to others on the market?
- Updated or outdated
- Floor plan
- Appliance packages
- How does the Master Suite compare to others on the market?
- Size
- First/second floor
- Updated or outdated
- Access to Master Bath
- How does the Master Bath compare to others on the market?
- Updated or outdated
- Shower and bath
- Flooring
Outside Areas:
- Are there views, outdoor living areas or recreational areas?
- How does the landscaping and hard-scaping compare to the market? (e.g., built elements such as walkways, patios, decks, etc.)
Overall Condition of Home
- What is the level of repair needed to compete with other homes?
- Does the home need to be staged? How does it show?
- What curb appeal projects are necessary to be consistent with others on the market?
Home Assessment Worksheet
If you want to accurately assess a home’s value, it’s crucial to know about the market activity of our local area. We can help! Give us a call at 303-475-6269 to get the scoop on the local market.
Sources:
- Investopedia http://www.investopedia.com/terms/a/assessedvalue.asp
- New York State Department of Taxation and Finance https://www.tax.ny.gov/pubs_and_bulls/orpts/mv_estimates.htm
- Realtor.com http://www.realtor.com/advice/sell/assessed-value-vs-market-value-difference/
- Investopedia, http://www.investopedia.com/articles/mortgages-real-estate/08/housing-appreciation.asp?lgl=myfinance-layout
SaveSave
SaveSave
by Farley Webmaster | Sep 29, 2016
The ‘smart home’ is the new ‘internet of things’, or objects that can serve you better by communicating with each other or directly with you through apps on your smart phone. In the ideal version of the wired future, all of our appliances and gadgets talk to each other seamlessly.
What could living in a smart home look like? Picture something like this:
The lights in your bedroom slowly illuminate to quietly awaken you in the morning, replacing the typical blaring alarm. The aroma of fresh brewing coffee drifts in and stirs your senses. Once the lights are all the way up, the heating system kicks on, just in time to warm up your room so you’re not shocked once you crawl out from underneath the duvet.
When you step into the shower, it turns on automatically and remembers your preferred temperature and water pressure. And it will shut off right when you’re finished as it knows how long you take to bathe.
Once you’ve driven out of your garage, your home alarm system arms itself. And it will only unlock automatically when it “sees” and recognizes someone else from your family approaching through programmed in biometrics.
Do smart homes really work this way right now? Not exactly…while you may find some of these smart features in certain homes, we haven’t reached the point where every feature intuitively knows what you want and when you wanted. However, each year we’re getting closer and closer toward that shiny, idealized ‘Jetson’ future.
Here are some trends that we see for smart homes, many of which may also help you save money:
Smart Thermostats
Programmable thermostats that are synchronized with the clock have been around for decades. However, they’re often difficult to set and aren’t necessarily efficient; they simply turn on or off as programmed, whether or not you are there.
With the newer models, smart thermostats can be programmed to adjust the temperature when they sense you are present. And once you leave, they can kick back to standby mode so that you’re saving energy and money. Nest does all of this, and it also allows you to check your usage from your cell phone so that you can adjust the temperature remotely and save even more.
Smart Smoke Detectors
Having a working, effective smoke detector saves lives. But unfortunately, many of us still have those battery-run smoke detectors that make that annoying, piercing beep when their batteries are running low on power. And instead of replacing batteries right away, it’s often easier to pull them out and disable the detector (while risking our lives).
Many of the new smart smoke detectors, like the Birdi, monitor smoke, carbon dioxide, as well as air quality. With this new sensor technology, they know the difference between a real fire and burnt toast.
Smart Sprinkler Control
Weather in our area is predictably unpredictable. Often, especially during the summer months, we fall into a severe drought. But then we might have one season that brings extreme amounts of rain, like we did this past spring.
A smart sprinkler controller like Rachio Iro can not only help save you lots of money on your water bill but also help protect our precious resources.
Programmable by computer or smart phone, it can automatically adjust how often you water your lawn based on the season and the weather forecasts. You can also remotely adjust the settings through a mobile app.
Smart Solar Panels
You can put the sun to work for you by using solar technology to power your home. It’s green and renewable, and can save you money over the long term. A recent study conducted by the NC Clean Energy Technology Center determined that Austin customers who invested in a solar system saved an average of $66 per month during the first year that they owned the system.
With smart solar panels, you can program the technology to monitor their performance and even turn them off in case of a weather emergency or fire.
Smart Home Security Systems
Home monitoring has become much more sophisticated in recent years. With the old-style security systems, you had to call in contractors to wire your home with monitoring sensors.
With new smart technology, you can simply place a few smart devices in your home to monitor movement and sense whether doors and windows are closed or opened. Some systems include audio and video monitoring, as well as sirens to scare off intruders. You get real-time feedback on security breaches through an app. And, because you’re alerted as soon as the system senses an intruder, it’s more likely that they will be caught.
Canary is one popular all-in-one audio-video security system, complete with sirens and night vision.
Smart Locks
Go beyond the standard key locks, which can often be compromised by burglars. The new smart lock systems give you more control over those who can gain access to your home.
Some systems, like the Kwikset Kevo, include encrypted virtual keys that you can program for access for a limited amount of time—for example, allowing guests over for a weekend, or cleaning service in during a specific window of time.
Other door locking systems include biometric technology. The Ola smart lock allows you to program your lock to recognize your family member’s fingerprints. Other systems use facial recognition to greet you and unlock your door.
The new August smart lock integrates with Apple’s technology so you can ask Siri to open your door for you.
Smart lighting systems and light bulbs
A well-lit home feels warm and welcoming, and good lighting can instantly increase the value of your home.
However, annual lighting costs can account for up to 12% of your overall electric bill, or over $200 per year according to Energy Star. You can easily reduce this expense simply by using smart lighting technology to add efficiency.
The Philips Hue wifi-enabled lights make it easy to add to your home without installing specialized equipment. Smart lighting dimmers and sensors can give you more control over how much energy you use and allow you to turn them on and off through your smart phone.
New smart light bulbs can give you control over the warmth or coolness levels of your lighting. With the Lifx LED light bulbs, for example, you can program your light bulbs to turn on or off when you want, to slowly wake you up with increasing illumination, or to change from daytime work lighting to entertainment-friendly shades for parties.
Smart Appliances
Programmable slow cookers and coffee makers are the quaint, old-fashioned versions of these home conveniences. Newer, smart appliances give you more control over how your food is kept and prepared, and make it easier for you to complete pesky household chores.
- Newer coffee makers, like the Smarter coffee machine, let you ‘order’ your coffee exactly to your liking, adjusting everything from bean grind to temperature to strength to time that it’s ready to drink.
- Smart refrigeration technology can help you store your food at just the right temperature, adjusting the thermostat during peak usage times. For example, the LG THINQ fridgecan alert you via smart phone app if a door is accidentally left open.
- Smart ovens can ensure that your food is cooked to the right level of done-ness, and alert you when your meal is ready to eat. June, a new counter oven invented by former Google, Apple, Go-Pro and Path employees will give you even more control—it will contain cameras, thermometers, and other technology to ‘learn’ what you like to eat and make menu suggestions.
- Smart washers and dryers have customizable controls so that you can safely wash any type of fabric. Some units include controls to increase drying time to save energy. And soon, connected appliances from GE, Oster, Samsung, and other makers, will be able to re-order soap and fabric softener directly from Amazon, so you won’t even have to think about running to the store at the last minute.
Have you tested any of these technologies in your home? Did we miss any of your favorite home technologies? Let us know in the comments!